Day spa insurance, across the whole menu
A day spa carries the standard pair, general liability for the premises and professional liability for the services, plus property coverage and workers compensation once there are employees. Two things set spas apart: wet areas raise the premises risk, and a wide service menu means the policy must be told about every service on it.
What coverage a salon needs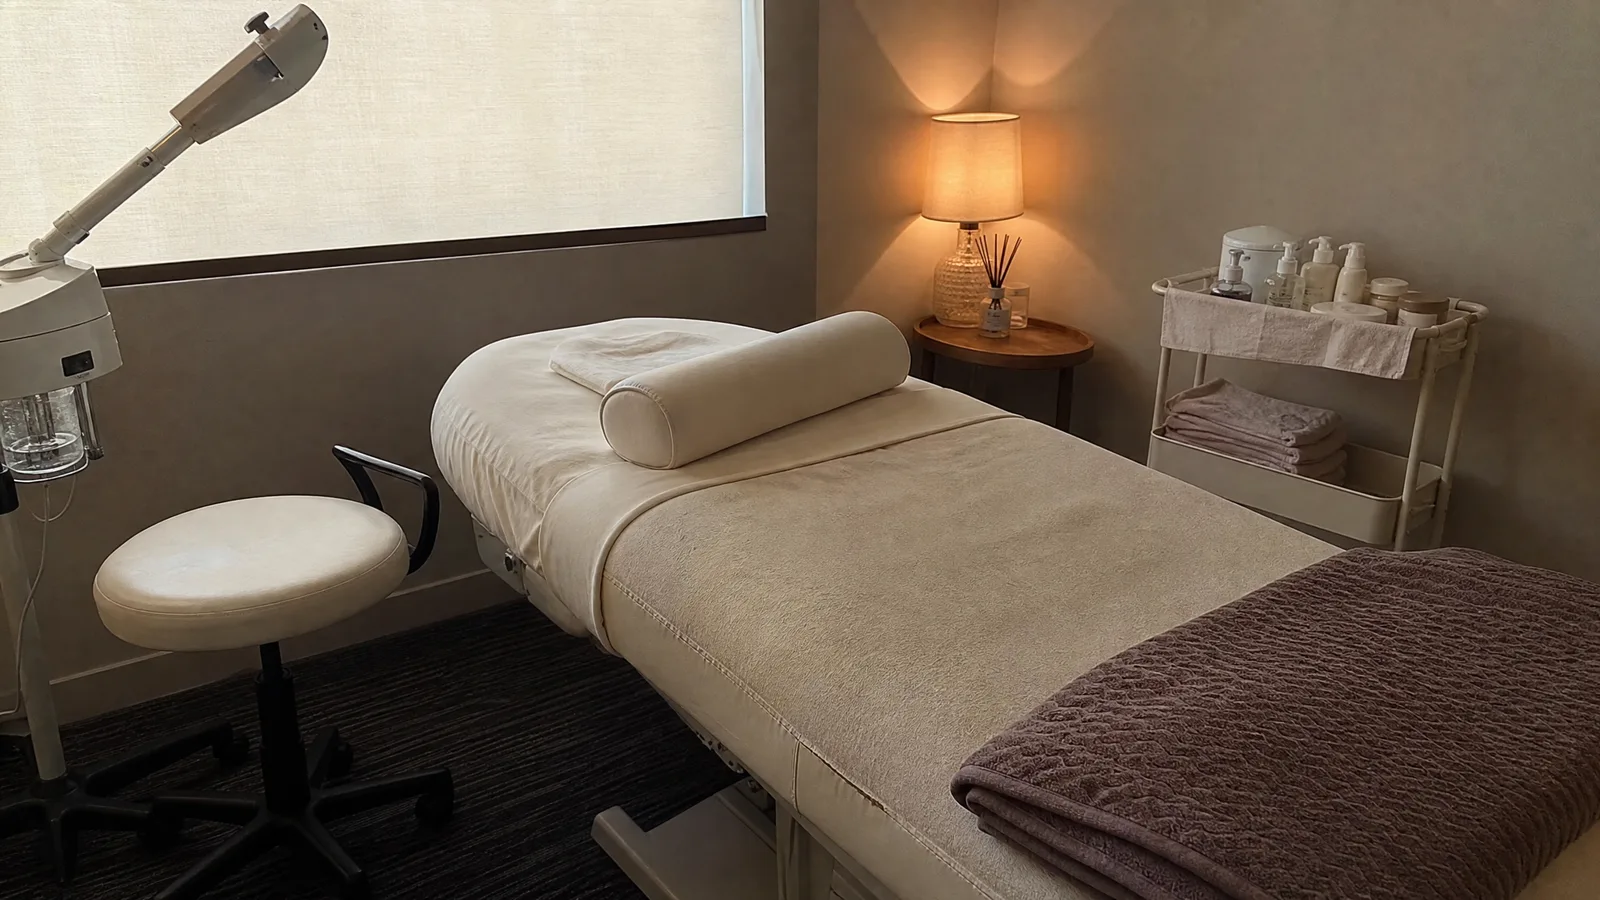
A premises risk with plumbing
General liability carries the premises: the NAIC's four categories, led by bodily injury and damage to others' property (NAIC, Insure U: Small Business Insurance). A spa's premises work harder than most. Showers, steam, soaking tubs, and tile mean wet floors are part of the product, and slip-and-fall is the textbook general liability claim. Flooring, signage, and maintenance practice are the facts an agent will ask about, because they are the facts a carrier prices.
The services carry the other half. A claim that a treatment itself caused harm, a facial, a body treatment, a wax, belongs to professional liability, which the NAIC lists among the risks a standard general liability policy does not protect against. The wider the menu, the more the professional side matters, and the more important the underwriting principle this site keeps repeating: a policy covers the services it was told about. List all of them, including massage and any esthetics work, when you ask for quotes. Treatment rooms bring one exclusion with them that a spa owner should read rather than inherit, and it is taken apart on massage insurance.
Property, packaging through a businessowners policy, and hiring all work as they do for any premises business; the walk-through on salon business insurance carries over, and workers compensation is required in nearly all states once you employ people. The practitioner-room version of the renter question is the same one salons handle: independent practitioners inside your spa are their own businesses, covered in our guide to insurance for booth renters.
The med spa line, stated plainly
Somewhere on the spa spectrum, the exposure stops being personal care. Injectables, lasers, and other treatments performed under medical supervision are generally treated as a medical exposure: a different placement, different underwriting, and the state medical board in the picture alongside the cosmetology board. This page does not cover that territory, deliberately. If any part of your menu is medical, lead with it in every insurance conversation, and work with an agent who places medical risks.
On the personal-care side of the line, licensing runs on the structure the whole industry shares: practitioner licenses separate from establishment licenses, state by state; Texas's program is one concrete example (Texas TDLR, Barbering and Cosmetology). Verify your own state's requirements with its board. For adjacent reading, the nail salon page covers the chemistry-heavy end of personal care, or start at the overview.